Geopolitical Tensions Put Pressure on Auditors and Regulators as Companies Grapple with the Effects of Sanctions and National Sovereignty
VIEW AS PDF

ACCOUNTING & AUDITING

By Don Carpenter, MSAcc/CPA

On February 24, 2022, Russian President Vladimir Putin invaded Ukraine in a move that had been anticipated for several weeks. And the ripples of this aggression were quickly felt throughout the world, with energy prices surging and food shortages worsening.

The destruction of the Ukrainian infrastructure has been massive. This force has been met with drastic economic countermeasures against Russia by Western countries on an unprecedented scale. But this is just one of several stress points putting strain on global relationships and highlighting just how interconnected we are.

Also capturing headlines for much of last summer were the simmering tensions between the People’s Republic of China and the U.S. over global expansion, fair trade and human rights. These tensions escalated with Speaker Nancy Pelosi’s visit to Taiwan in August, which caused the Chinese government to cease talks with the U.S. on both economic and military topics. Although these issues seem far away from the world of financial reporting, they present thorny issues for regulators who are responsible for the integrity of the system.

Since the start of the Ukrainian invasion, several hundred international businesses have mothballed their operations in Russia or pulled out completely. This has led to material financial losses that are potentially subject to considerable judgement. It is difficult to assess future cash flows under the circumstances for purposes of impairment testing and going-concern issues. Further, the question of whether non-Russian owners retain legal title to assets after the pullout remain murky at best.

Making matters worse, the pullout was not limited to consumer-facing businesses. Advisory and financial firms with branches in Russia have also come under directives to sever ties in the country. The Big Four and other global firms have cut or are in the process of cutting ties with their Russian affiliates. The major accounting firms are a group of national firms bound by agreements under one common brand.

With the imposition of sanctions, the international network began severing their relationship with their Russian affiliates. This separation introduces inefficiencies and risks with regard to auditing clients’ Russian businesses. If the U.S.-based audit firm relies on the work of the now-independent Russian affiliate, the U.S. auditor must apply higher standards to the work performed in Russia since it will be relying on the work of an independent party.

Sanctions by the U.S. and its allies also require that auditors no longer provide service to businesses or individuals in Russia. To avoid a violation of these sanctions, U.S. audit firms are requesting representations from their clients that they have no significant ties with Russian nationals or companies. In what some are calling “overkill,” these representations may even include a request that the client verify that no Russian national or resident owns 5% or more of the company’s shares.

However, there are limits to the sanctions. Firms are allowed to audit the U.S. subsidiaries of Russian companies or branches of Russian businesses located in the U.S. But given the potential impact on a firm’s reputation, most firms appear to be erring on the side of caution when it comes to continuing any ties to Russian commerce.

The difficulties reach into Ukraine, as well. Since the dissolution of the U.S.S.R. in 1991, trade between the former Soviet republics on the one hand and Western nations on the other has mushroomed. Ukraine has been at the forefront of this, given its location and vast resources. U.S. companies in pharmaceuticals, energy, financial services and chemicals have investments in the country. Other entities may have no direct investment but rely on Ukrainian exports as a critical part of the supply chain. As a result of the war, U.S. audit firms may have difficulty relying on local Ukrainian audit firms or members of their international network to complete even basic attest functions given the destruction of property, records and systems.

Moving further east, the Public Company Accounting Oversight Board (PCAOB), which is responsible for reviewing the quality of audits of public companies, has confronted another set of issues regarding Chinese companies listed on U.S. exchanges. Well over 200 Chinese companies are traded on U.S. markets via the American Depository Receipt system. The audits of these companies’ financial results are prepared by Chinese firms. However, the audits are subject to review by U.S. firms under the standards set by PCAOB.

The Chinese authorities have been reluctant to release the audit workpapers, citing concerns over national security. PCAOB has reiterated to U.S. firms that it will not accept any restrictions on access to the Chinese firms’ work. As tensions increased, several prominent Chinese firms indicated that they were prepared to delist from U.S. exchanges. In an 11th hour move, PCAOB and the China Securities Regulatory Commission announced an agreement to allow inspection of local audits on-site of firms selected unilaterally by PCAOB.

Auditors confronted with any of these circumstances must consider their impact on the quality of the audit since they represent a scope limitation. Any limitation in the Russian-Ukrainian conflict may not be insurmountable if it is deemed immaterial.

However, in the case of the Chinese restrictions, lack of access to the audit workpapers would by its nature be material. Any scope limitation that is material will likely require a qualified opinion even though the circumstances are beyond the control of the client.

It is unclear how the Securities and Exchange Commission (SEC) will react to a qualified opinion caused by war. But in the case of the Chinese refusal to provide documentation, delisting of the companies is a distinct possibility if the recent agreement proves unsatisfactory.

It should be emphasized that companies and their auditors should not overlook global issues when considering the impact on the financial reporting obligations they undertake.

About the Author: Don Carpenter is clinical professor of accounting at Baylor University. Contact him at Don_Carpenter@baylor.edu.


  • Workforce Development

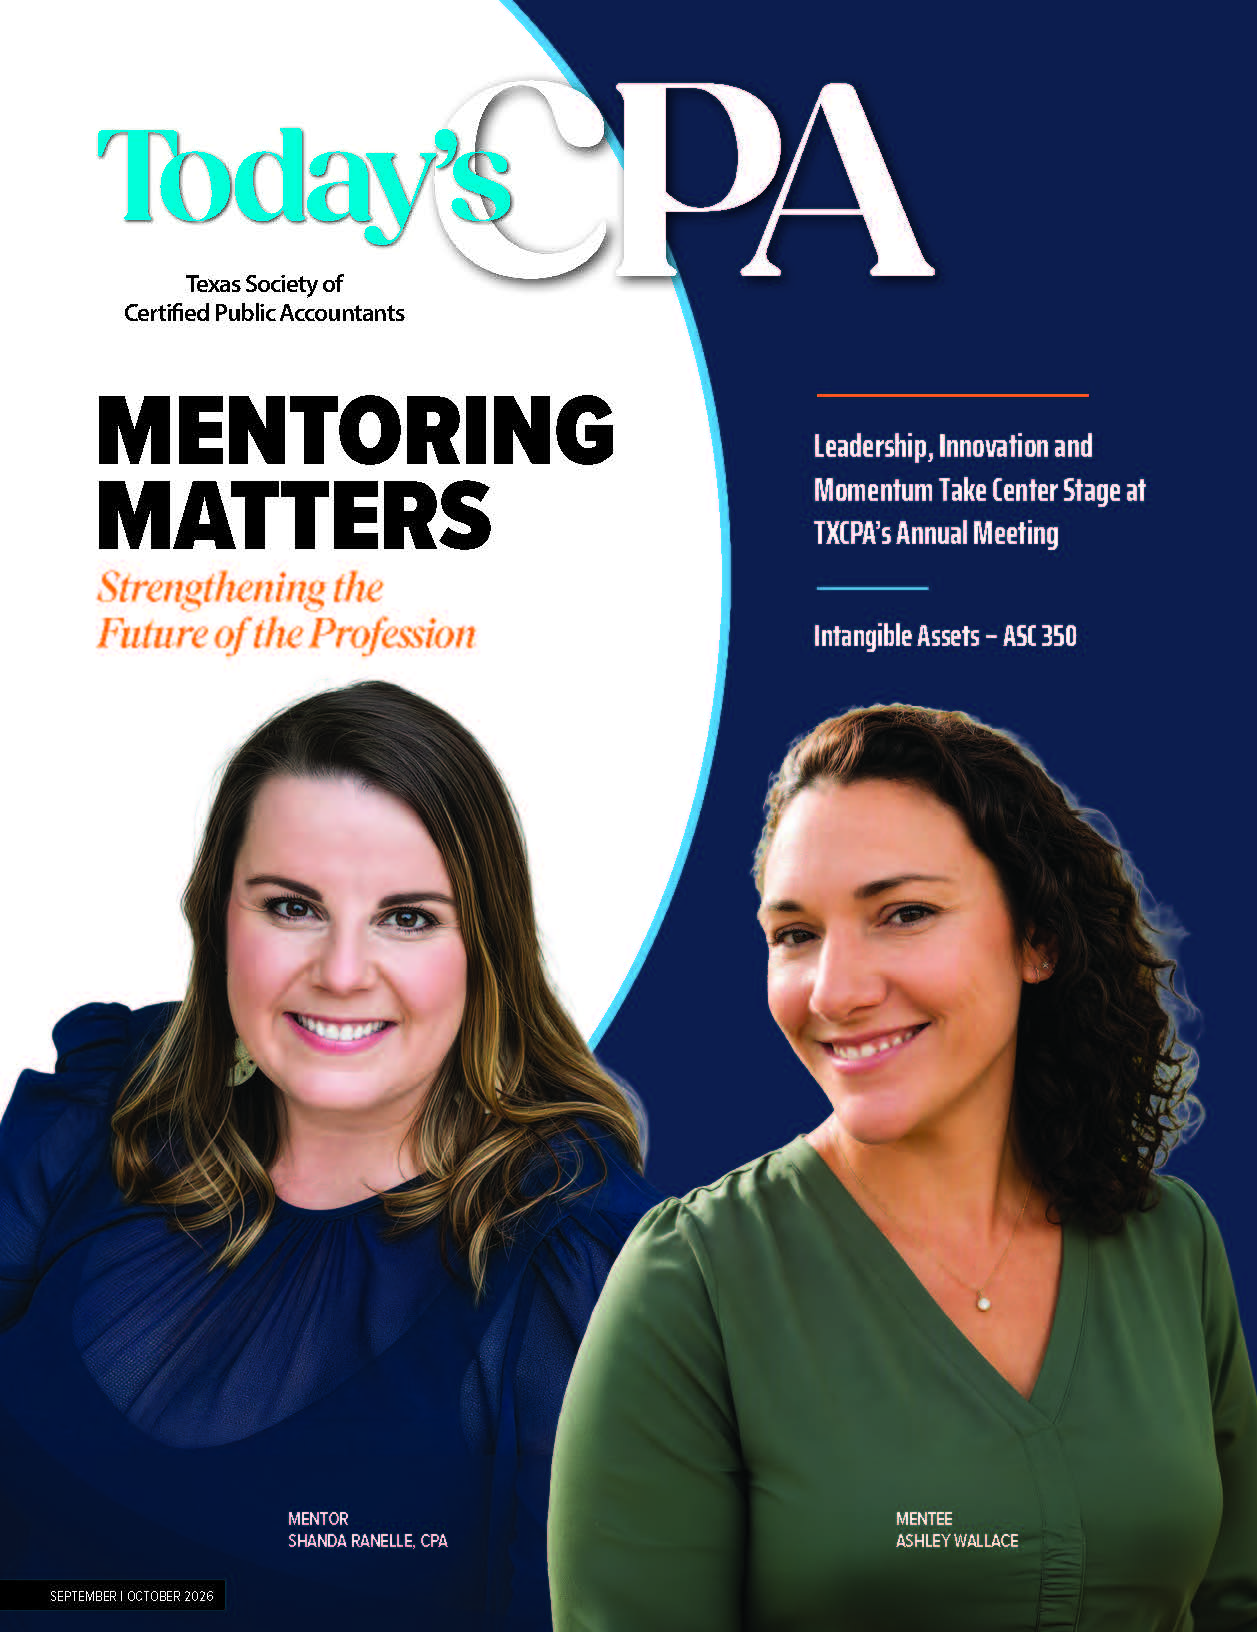
    Mentoring Matters: Strengthening the Future of the Profession

    Mentoring is a cornerstone of the accounting profession. From supporting students and CPA candidates to accelerating the growth of experienced professionals, mentoring strengthens confidence, preserves institutional knowledge and prepares future leaders. TXCPA's Mentor Match program is designed to help members build meaningful professional relationships that support their career growth and development.
    View Article
  • CPE: Intangible Assets – ASC 350

    FASB’s recent targeted GAAP improvements address the accounting and reporting of internally developed software. ASU 2025‑06 replaces development‑stage rules for internal‑use software with a “probable‑to‑complete” capitalization threshold.
    View Article
    IPR&D
  • volunteer leadership

    Leadership, Innovation and Momentum Take Center Stage at TXCPA's Annual Meeting

    TXCPA’s 2026 Annual Meeting brought more than 200 leaders together to celebrate organizational achievements, discuss emerging trends and shape the future of the organization. As the organization enters the final year of its Strategic Plan, the meeting emphasized momentum, collaboration and continued involvement in TXCPA and the accounting profession.
    View Article
  • Expanding the CPA Pipeline: An Important Joint Initiative for CPA Firms and K-12 Schools

    CPA firms, universities and professional organizations are using coordinated efforts to expand the future CPA talent pipeline by reaching students much earlier in the K‑12 system. Because many students choose career pathways as early as 8th grade, the authors emphasize shifting outreach toward freshmen and sophomores already inclined toward business studies.
    View Article
    TXCPA Accounting Opportunities Month
  • Workforce Development

    Mentorship, Momentum and the Future of the Profession

    Strong connections are essential to the future of the CPA profession. This CEO's Message highlights the power of mentorship, TXCPA’s efforts to strengthen the accounting pipeline, and the many ways members, volunteers and chapters are helping build opportunities for the next generation of CPAs.
    View Article
  • Outstanding Chapter Awards Recognize Achievements in Leadership and Service

    TXCPA’s Outstanding Chapter Awards recognize small and medium-sized chapters for excellence in leadership, member service, innovation and community involvement. The 2025-26 recipients, TXCPA Rio Grande Valley and TXCPA East Texas, were honored for their strong student outreach initiatives, professional development opportunities, scholarship fundraising, member engagement and community service.
    View Article
    volunteer leadership
  • Workforce Development

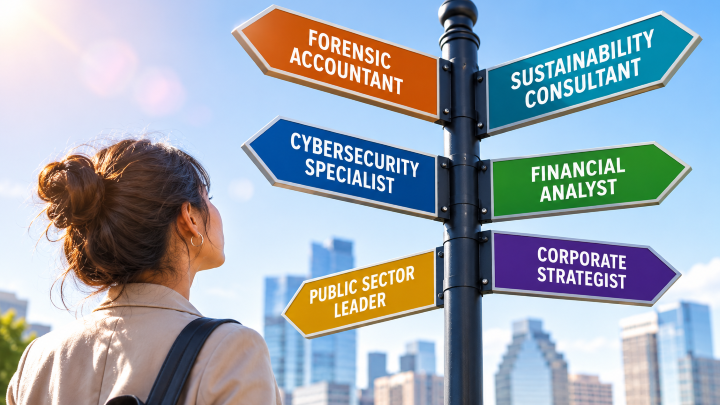
    Beyond Tax and Audit: Shedding Light on Alternative Career Pathways

    Accounting offers far more career opportunities than traditional tax, audit and financial reporting roles. By introducing students to the diverse ways accounting skills can be applied, educators and practitioners can help the next generation of CPAs see the many possibilities an accounting career can offer.
    View Article
  • What’s Happening Around Texas - September-October 2026

    TXCPA chapters across Texas are strengthening connections through student engagement events, legislative conversations, member appreciation gatherings, and strategic planning sessions. From Corpus Christi’s student bowling mixer and to Southeast Texas’ celebration with Lamar University to El Paso's and San Antonio’s focused planning meetings and Victoria’s community‑building event, each chapter is fostering momentum, collaboration and professional growth.
    View Article
    TXCPA Chapters
  • Tenure

    Is Accounting Academia Still a Good Career Option for CPAs? An Updated Perspective

    Is accounting academia still an attractive career path for CPAs? Although demand for accounting Ph.D. graduates has declined despite earlier predictions of faculty shortages, accounting professors continue to enjoy strong compensation, work/life balance, tenure stability and summer flexibility.
    View Article
  • Spotlight Article: Leading Beyond the Numbers

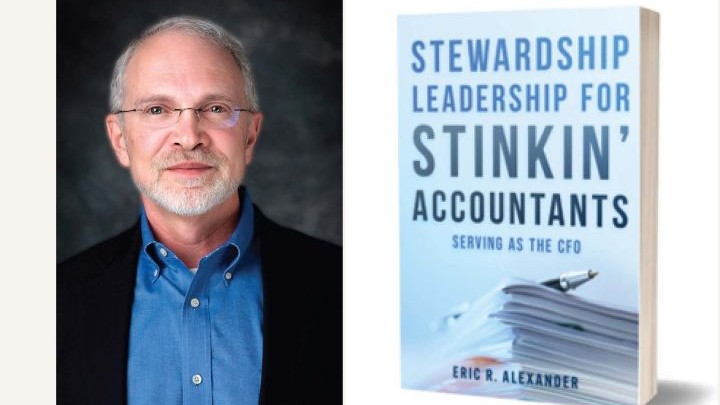
    Eric R. Alexander discusses the lessons behind his book “Stewardship Leadership for Stinkin' Accountants: Serving as the CFO” and how a servant mindset, wisdom and relationships create a lasting impact. He explores why trust, accountability and communication are essential to effective financial leadership, especially as AI transforms the profession.
    View Article
    Strategic Planning
  • Sustainability reporting

    Assessing Materiality of ESG Risks: Guidance for CPAs

    This article explains how CPAs can assess and disclose material environmental, social and governance (ESG) risks that may affect a company’s financial position, operations and stakeholders. The concept of double materiality is introduced, which considers both the financial impact of ESG risks on a company and the company’s impact on society and the environment.
    View Article
  • PCC Addresses Priority Private Company Issues in Q2

    This update summarizes the Private Company Council (PCC) activities for the second quarter of 2026. During its June meeting, the council prioritized improving financial disclosures for Employee Stock Ownership Plans (ESOPs) and targeted lease accounting simplifications for private companies, and discussed FASB's decision to add a project on subjective acceleration clauses and debt default disclosures.
    View Article
    Private Company Council
  • volunteer leadership

    Leading the Way: TXCPA Thanks Our 2026-2027 Faculty and Student Ambassadors

    TXCPA celebrates and thanks our 2026–2027 Faculty and Student Ambassadors, whose leadership and enthusiasm bring our programs, resources and opportunities directly to campuses across Texas. Their commitment strengthens our connection to future professionals and fuels the growth of the CPA pipeline statewide.
    View Article
  • Profitable Is Not the Same as Valuable

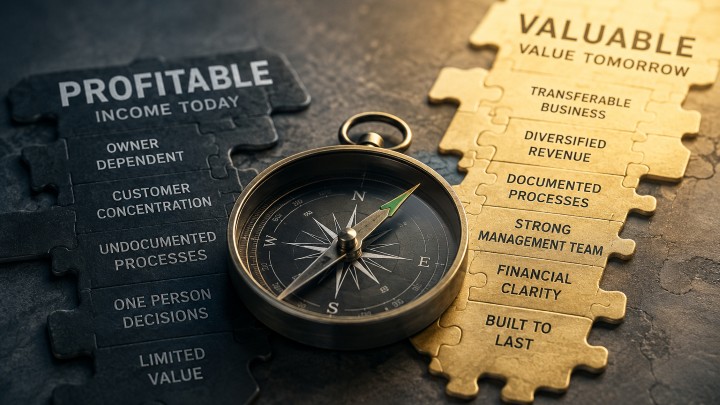
    A profitable business is not necessarily a valuable or transferable one, as enterprise value depends on organizational architecture rather than dependence on the owner’s involvement. The central message: profitable operations generate income, but only well‑structured businesses build equity that can be sold, transferred or relied upon for retirement.
    View Article
    valuation
  • Workforce Development

    A New Era for CPA Licensure in Texas – and a Look Ahead

    Texas has entered a new phase of CPA licensure with the implementation of Senate Bill 262 on August 1, 2026, creating an alternative pathway that allows candidates to qualify with 120 hours of education and two years of experience, alongside the traditional 150‑hour route. As the 2027 legislative session approaches, TXCPA is preparing to protect strong licensing standards, monitor deregulation efforts and engage newly elected lawmakers.
    View Article
  • Take Note

    In this edition of Take Note: A Legacy of Mentorship - A Tribute to John Baines, CPA-Dallas; Accountants Confidential Assistance Network (ACAN); CGMA® Designation; TXCPA Member Insurance
    View Article
    TXCPA Member Insurance
  • Virtual Accounting

    Classifieds

    The Classifieds section of Today's CPA provides a one-stop destination to find practices for sale, connect with buyers, and access services that support growth, transition and market expansion.
    View Article


CHAIR
Angela Ragan, CPA

PRESIDENT/CEO
Jodi Ann Ray, CAE, CCE, IOM

CHIEF OPERATING OFFICER
Melinda Bentley, CAE

EDITORIAL BOARD CHAIR
Derrick Bonyuet-Lee CPA, CGMA

MANAGER, MARKETING AND COMMUNICATIONS
Peggy Foley
pfoley@tx.cpa

MANAGING EDITOR
DeLynn Deakins
ddeakins@tx.cpa

CLASSIFIEDS
DeLynn Deakins
ddeakins@tx.cpa

Texas Society of CPAs
14131 Midway Rd., Suite 850
Addison, TX 75001
972-687-8550


EDITORIAL BOARD
Derrick Bonyuet-Lee, CPA-Austin;
Drew Chumley, CPA-Fort Worth;
Adam Dimmick, CPA-Houston;
Julia Frink, CPA-Fort Worth;
Baria Jaroudi, CPA-Houston;
Jeffrey Johanns, CPA-Austin;
Brian Johnson, CPA-Central Texas;
Michael Kraten, CPA-Houston;
Lucas LaChance, CPA-Dallas;
Shilpa Boggram Sathyamurthy, CPA-Houston.

CONTRIBUTORS
Melinda Bentley; Kenneth Besserman; Holly McCauley; Shicoyia Morgan; Craig Nauta; Triniti Patterson